
OTTAWA – Canadist: Canada No Credit History Renting: How Newcomers Can Find Housing
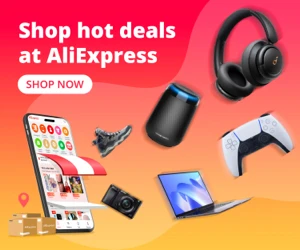
For newcomers arriving in Canada, securing a first rental can be difficult even when they have a job, savings and years of responsible financial activity abroad. The problem is often not an inability to pay, but the absence of a Canadian credit record that a landlord can easily verify. What can newcomers do when a rental application asks for a credit history they have not yet had time to build?
The issue has become an increasingly important part of the wider newcomer housing debate. A Royal LePage survey of 1,400 newcomers who arrived in Canada within the past decade found that 33 per cent currently own their primary residence, while 66 per cent do not own any property. Among those who want to buy but have not yet done so, 27 per cent said building a credit score or credit history was a barrier.
For many people, however, the first hurdle comes before homeownership. It is finding a place to rent.
Canada No Credit History Renting: Why newcomers face a difficult first application
Canadian credit history does not automatically transfer from another country.
A newcomer may have spent years paying rent, mortgages, loans or household bills on time in their previous country. They may arrive with savings, a confirmed job and a strong financial record. Yet a landlord conducting a Canadian credit check may find little or no information about them.
That creates an information gap.
Credit checks are commonly used as one way of assessing whether a prospective tenant is likely to pay rent on time. When there is no Canadian record, the landlord has less information with which to assess that risk. The Canada Mortgage and Housing Corporation explains that someone who has never had a loan or credit card can have little or no information in their credit file for a landlord to review.
The absence of a credit history does not automatically mean an applicant cannot rent.
Instead, newcomers often need to demonstrate financial reliability through other documents and references. Federal guidance also recognizes that people without Canadian employment, references or credit history may need assistance from newcomer settlement organizations.
The key is to replace missing information with credible evidence.
An employment letter can demonstrate current or expected income. References from a previous landlord can show a history of responsible renting. Evidence of savings may demonstrate that the applicant has the resources to meet rental payments.
Recent newcomer housing guidance continues to emphasize the importance of presenting a strong application when a Canadian credit record is unavailable. Recent reports and housing guides also point to employment letters, proof of funds and references as practical alternatives landlords may consider.
The precise requirements vary from one landlord to another, while rental legislation differs across provinces and territories.
That means newcomers should avoid assuming that one landlord’s requirements apply everywhere in Canada.
What landlords are really trying to establish
Behind a credit check, a landlord is generally trying to answer a straightforward question: can this applicant reliably meet the financial obligations of the tenancy?
A strong newcomer application should therefore answer several questions before the landlord needs to ask them.
Where does the applicant work? What income do they have? Do they have savings? Can someone provide a reference? Is there a guarantor? Can previous rental history be verified?
The more clearly those questions are answered, the less the application has to rely on a Canadian credit score alone.
Canada No Credit History Renting: Documents that can strengthen an application
Newcomers can improve their chances by preparing their rental documents before beginning the search.
An employment letter is one of the most useful pieces of evidence for someone who has recently started working in Canada. It can establish the employer, position and income and show that the applicant has entered the Canadian labour market.
A signed job offer can also be relevant for someone who has not yet received Canadian paycheques.
Proof of funds may provide another indication of financial capacity. Bank statements can demonstrate available savings, although applicants should disclose financial information carefully and only when appropriate. Sensitive banking credentials should never be provided to an unknown advertiser.
References can also help fill the gap created by a missing Canadian rental history.
A former landlord from another country may not provide exactly the same information as a Canadian reference, but the reference can still demonstrate that the applicant has rented before and maintained a responsible tenancy. Professional or employment references may also help, depending on the circumstances.
The goal is not to overwhelm a landlord with paperwork. It is to provide enough credible information to make the application understandable.
A guarantor can make a difference
For some newcomers, a guarantor can provide another route around the absence of Canadian credit.
The Canada Mortgage and Housing Corporation says someone without a credit rating may use a guarantor who agrees to assume responsibility if the tenant fails to pay. A parent, close friend or another eligible person may take that role depending on the circumstances.
A guarantor is more than a character reference.
The person may carry financial responsibility under the rental arrangement, so anyone considering the role should understand the commitment before signing.
For newcomers who have family or close friends already established in Canada, this can be an important option. For those arriving without an existing Canadian network, finding a suitable guarantor can be much harder.
That is why settlement organizations and community networks can play an important role during the first months after arrival.
Shared housing can provide another route
Shared accommodation can also reduce some of the pressure facing a newcomer who cannot immediately qualify for a conventional apartment.
A joint lease with an established tenant may be possible in some situations. Subletting can also operate differently from applying directly for a new tenancy.
However, the legal requirements depend on the province or territory and the precise housing arrangement.
Newcomers should therefore understand who is legally responsible for the rent, whether the landlord has approved the arrangement where required and what rights the tenant has under local rules.
Federal newcomer guidance recommends considering shared housing, rental agencies, online advertisements, community resources and newcomer service providers when searching for accommodation.
Competition makes the search harder in major newcomer destinations
The lack of Canadian credit history is only one part of the problem.
Newcomers are also entering rental markets where demand, affordability and competition can make finding a suitable home difficult.
Toronto and Vancouver remain major destinations for new immigrants despite their high living costs. Reporting based on Statistics Canada census information has found that more than 40 per cent of recent immigrants have settled in those two metropolitan areas each year since 2016.
For a newcomer, that concentration can create an additional disadvantage.
An applicant without Canadian credit may be competing against another tenant who already has a Canadian employment history, rental references and established credit.
The newcomer may still be financially stronger than some competitors, but the landlord may have more easily verifiable information about the other applicant.
That can make preparation particularly important.
A newcomer who waits until after a property viewing to begin gathering documents may lose valuable time. Rental markets can move quickly, and landlords may receive several applications for the same property.
Preparing a complete application in advance can make it easier to respond when a suitable home becomes available.
Recent Canadian newcomer-focused reporting has similarly highlighted the value of employment documentation, proof of funds and references for applicants without local credit or rental histories.
Flexibility can widen the options
A newcomer who searches only within one neighbourhood, for one apartment size and within a very narrow price range may face a longer wait.
Considering shared accommodation, different neighbourhoods or a temporary rental can provide additional options.
But flexibility should never mean accepting unsafe housing or ignoring legal protections.
A lower advertised rent may not represent a better deal if the property is far from work, public transportation, schools or essential services.
Transportation costs and commuting time can significantly change the real cost of accommodation.
That is particularly important for newcomers who have just started employment and need reliable access to work.
How newcomers can search without relying on a credit score
There is no single route that works for every newcomer.
Federal guidance recommends several ways to search for housing, including asking friends and acquaintances, checking online advertisements and social media, contacting rental agencies, looking at community resources and seeking assistance from newcomer service providers.
Personal networks can sometimes provide introductions to landlords or existing tenants.
Settlement organizations can offer information about local housing practices and help newcomers understand what documents they may need.
Rental agencies can provide another channel, although applicants should understand any fees, obligations or agreements before proceeding.
Online listings can offer a much wider choice, but they also require caution.
A professional-looking advertisement does not prove that the property is legitimate.
Newcomers should be especially careful when someone demands money before the property has been properly verified or refuses to arrange a credible viewing.
They should also avoid sending unnecessary identity or financial documents to unknown individuals.
The basic principle is simple: verify the property, verify the person offering it and understand the rental agreement before transferring money.
Looking beyond Toronto and Vancouver
The pressure in Canada’s largest newcomer destinations has encouraged some people to consider smaller communities.
That can sometimes make housing more accessible, but moving away from a major city is not automatically the answer.
Employment opportunities, transportation and access to essential services remain important considerations.
A recent report from the Huron-Perth region described difficulties faced by newcomers who lacked Canadian credit histories, local references or previous Canadian landlords. Some turned to guarantors or shared accommodation to overcome those barriers.
The example illustrates a wider issue.
Housing affordability cannot be judged by monthly rent alone. A cheaper home can become more expensive if a tenant has to spend significantly more on transportation or cannot easily reach work.
For newcomers, the best location may therefore be the one that balances rent, employment, transportation and access to community services.
What happens after the first rental?
Securing the first Canadian rental is only the beginning of the process.
Once a newcomer establishes a Canadian rental record, employment history and broader financial footprint, future housing applications may become easier.
Building Canadian credit can also become part of a longer-term financial strategy.
Research cited in recent newcomer housing reporting shows that homeownership tends to increase as immigrants spend more time in Canada. The Royal LePage survey found that 45 per cent of respondents who had been in Canada for five to 10 years owned a home, compared with 22 per cent among those who had been in the country for fewer than five years.
The figures do not mean every newcomer will follow the same path.
They do, however, show why the first rental can be an important foundation.
A newcomer should not feel pressured to take on unnecessary debt simply to create a credit history. The purpose of building credit is to establish a reliable financial record, not to borrow money for its own sake.
Responsible use of financial products and regular payments can gradually create the Canadian financial history that was missing on arrival.
Keep a record of successful renting
A newcomer who keeps copies of rental agreements, payment records and landlord references can gradually build a stronger housing profile.
That record can become useful when moving to another apartment, seeking a larger property or eventually applying for financing.
A positive relationship with a landlord can also lead to a reference for the next application.
In that sense, the first tenancy can serve as more than a place to live. It can become part of the documentation that supports future housing decisions.
Canada No Credit History Renting: Understanding tenant rights
Not having a Canadian credit history does not remove a tenant’s legal protections.
Rental rules vary across Canada because residential tenancy matters are governed primarily at the provincial and territorial level.
That means rules concerning deposits, screening, leases, notices and disputes can differ depending on where the property is located.
Newcomers should therefore check the rules that apply in their province or territory before signing a rental agreement or agreeing to unusual payment conditions.
The federal newcomer housing guidance directs tenants toward provincial and territorial rental authorities and provides information on finding accommodation and understanding the rental process.
Applicants should not assume that a landlord’s demand is legal simply because the landlord describes it as normal.
Before paying money, newcomers should understand how much rent is required, what deposit is being requested, what the lease says and what responsibilities belong to the landlord and tenant.
They should also keep copies of important communications, receipts and agreements.
This documentation can become valuable if a disagreement later develops.
The most practical strategy for newcomers
For newcomers with no Canadian credit history, preparation may be the strongest advantage available.
The first step is to assemble evidence of income and financial stability.
The second is to identify references and, where possible, a legitimate guarantor.
The third is to remain flexible about neighbourhoods, apartment types and shared accommodation while the Canadian financial and rental record develops.
The fourth is to use established newcomer and settlement services rather than relying entirely on unfamiliar online listings.
The fifth is to verify the property, the person offering it and the legal requirements before transferring money.
Recent reporting and newcomer housing resources point to the same basic conclusion: a missing Canadian credit score is a hurdle, but it does not necessarily close the rental market. Employment evidence, savings, references, guarantors and a carefully prepared application can give landlords other information on which to assess an applicant.
The broader housing picture also shows why the first rental matters.
For someone arriving with savings, employment prospects and a strong financial history abroad, the challenge is to translate that record into evidence that a Canadian landlord can understand.
That process takes time.
A newcomer should not interpret the absence of a Canadian credit score as proof of financial unreliability. In many cases, it simply means the person is new to the country.
The strongest response is preparation: build the application before the search begins, understand local rental rules, protect personal information, verify listings and use credible evidence to demonstrate the ability to pay.
For many newcomers, the first Canadian rental will not be the final destination. It can instead be the first step toward a stable housing record, stronger financial history and, eventually, greater housing choice.
FAQ
Can I rent in Canada without a credit history?
Yes. Some landlords may consider employment, income, savings, references, a guarantor or other evidence instead of relying solely on Canadian credit history.
Can a guarantor help a newcomer rent a home?
Yes. A guarantor can assume financial responsibility under a rental arrangement if the tenant fails to meet their obligations.
Where can newcomers search for rental housing?
They can use online listings, rental agencies, community resources, personal networks and newcomer settlement organizations.
Do rental rules apply equally across Canada?
No. Residential tenancy rules vary by province and territory, so applicants should check the regulations that apply to the property they want to rent.
Contact: info@canadaalyom.com